
Long-Term Care
Why Should I Consider Long-Term Care When Preparing For Retirement
Someone turning 65 today has almost a 70% chance of needing long-term care at some point in their lives. After the first year, the average person receives care for an additional 3.5 years. The average life expectancy of someone diagnosed with Alzheimer’s is 4-8 years.
What Questions Should You Be Asking Yourself?
How could a long-term care need affect my family and my retirement strategy? Where should I consider receiving care?
What could it potentially cost? What are my options in covering that cost?
Public Programs
- Medicare, Medicaid, and other federal or state-sponsored programs.
Informal Care
- A known and trusted individual such as a family member or friend to take care of them
Formal Care
- Assisted Living Facilities
- Nursing Homes
- Qualified in-home care
- Adult day care
Considerations of Public Programs
- May require a hospital stay
- May require an individual to spend down their assets in order to qualify
- Coverage can be limited
Considerations of Informal Care
- Availability
- Proximity
- Physical, financial, or emotional impact to caregiver
Considerations of Formal Care
- Type of service desired
- Cost of service
- Who will oversee care?
Long-Term Care Coverage Options
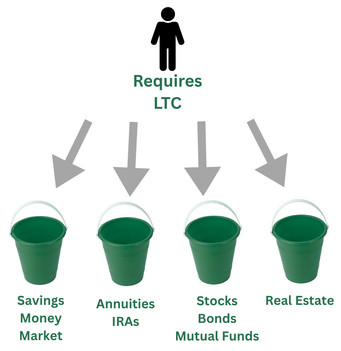
Self-Funding
- Dedicates a portion of your portfolio to address long-term care needs
- Potential risks include market volatility, inflation and other income needs
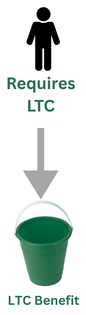
Traditional Long-Term Care Insurance
- Various needs and benefits
- Reimburses costs of qualified care
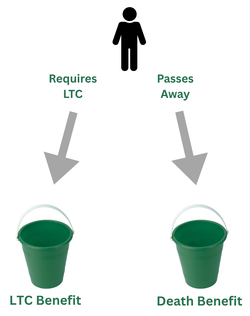
Life Insurance with an Optional LTCi Rider
- Death benefit acceleration for LTC services
- May be used for formal or informal care, depending on product
- Premium may be flexible or guaranteed not to increase, depending on the product
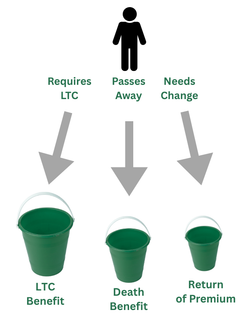
Linked Benefit Products
- Long-term care benefits are usually larger than the life insurance policy death benefit
- Premiums are guaranteed not to increase
- Potential for Return of Premium Option
What
are My
Next
Steps?
- Think about a written strategy
- Discuss it with your Licensed Insurance Professional
- Plan for how you would fund your strategy
- Solutions should include:
Benefit Amount
Benefit Period Length
Type of Care Received
Inflation and Rising Costs of Care
Potential Financial Impact on Current Retirement Strategy


